How to Build Credit From Scratch: A Guide for First-Time Account Holders
| Key Takeaways
• Your score affects loans, jobs, insurance, and even renting. • Payment history and utilization drive 65% of your score. • An authorized-user credit card and an ABC account are strong starts. • Expect a first score in six months, real gains within two years. |
Your credit score follows you into more parts of life than you might expect. It shapes which loans you qualify for and the interest rate you pay, but it can also affect whether you land a job, rent an apartment, or get a good deal on insurance.
If you’re a teenager or just starting your first job, still in school, or rebuilding after a setback, it’s easy to feel like you don’t know where to begin. This guide covers what a credit score actually is, the realistic ways to start building one, and the habits that keep it healthy once you have it.
Why You Need a Good Credit Score
A good credit score does more than help you qualify for a credit card or a car loan. It also determines the interest rate you’re offered, which can add up to real money over time. It matters beyond borrowing, too. The Consumer Financial Protection Bureau notes that many employers check credit reports as part of a background check, so a thin or troubled file could cost you a job offer. Insurers use it as well: the National Association of Insurance Commissioners reports that roughly 95% of auto insurers and 85% of homeowners insurers factor credit into premiums where state law allows it. Landlords often check credit too, which means your score can influence where you’re able to live.
What a Credit Score Actually Measures
Think of your credit score as a report card: a three-digit number that tells lenders how likely you are to pay back what you borrow.
These scores, often called FICO scores, come from the nation’s three credit bureaus: . You can check all three for free, once a week, at without it affecting your score.

If you don’t have a credit history yet, that’s normal, not a red flag. It just means there’s nothing on file for lenders to evaluate, and the sections below cover how to change that.
It’s still worth pulling your report at least once a year to track your progress and catch identity theft early. If you spot an account or loan you don’t recognize, contact the bureau that’s listing it. Errors like this can drag your score down and are sometimes the first sign that someone has stolen your identity.
What Determines Your Credit Score
According to , the company behind the FICO Score, your score is built from five factors:
- Payment history, whether you pay bills like loans and utilities on time: 35%
- Amounts owed, often called credit utilization: how much you owe compared to your total available credit across cards and loans: 30%
- Length of credit history, how long you have held your accounts: 15%
- Recent applications for credit: 10%
- Credit mix, the variety of loan types you carry: 10%

Why “No Credit History” Isn’t the Same as Bad Credit
Having no credit history isn’t the same as having bad credit, and it’s a common starting point if you’ve never had a loan or credit card in your own name. Most people establish a first score within about six months of opening a reportable account. Bad marks, by contrast, stick around: the that negative information like late payments can stay on a report for seven years, and bankruptcy for ten. That’s exactly why it pays to build good habits from the start rather than repair damage later.
Practical Ways to Start Building Credit
If a parent or family member has good credit, becoming an authorized user on their credit card is often the easiest first step. You’ll get a card in your name, and in most cases, their account’s payment history will show up on your credit report. That said, not every credit card issuer reports authorized-user activity to the credit bureaus, so it’s worth confirming with the issuer before you count on this as your main strategy.
Your checking and savings accounts won’t build your credit score directly, since the bureaus don’t track deposit account activity. But a steady, well-managed account with ABC Bank still does real work for you: it builds a banking history you can lean on when you’re ready to apply for your first credit card or loan, and it gives you the proof of income and steady funds most first applications ask for. Overdrafts and unpaid negative balances are a different story. Those can be reported to , a separate agency banks use to screen new account applications and can follow you to your credit report if they end up in collections. Keeping your balance in the black protects both your banking history and your credit.
Many credit card issuers also offer student credit cards, which typically do not require an existing credit history and come with lower limits while you are getting started. If you are in school, pairing one of these with your ABC checking account is a straightforward way to build a payment history.
If you rent, some services report your on-time payments to the credit bureaus for a monthly fee. Start by asking your landlord if they already use one. If you sign up on your own, check how many bureaus that service reports to first, since coverage varies.
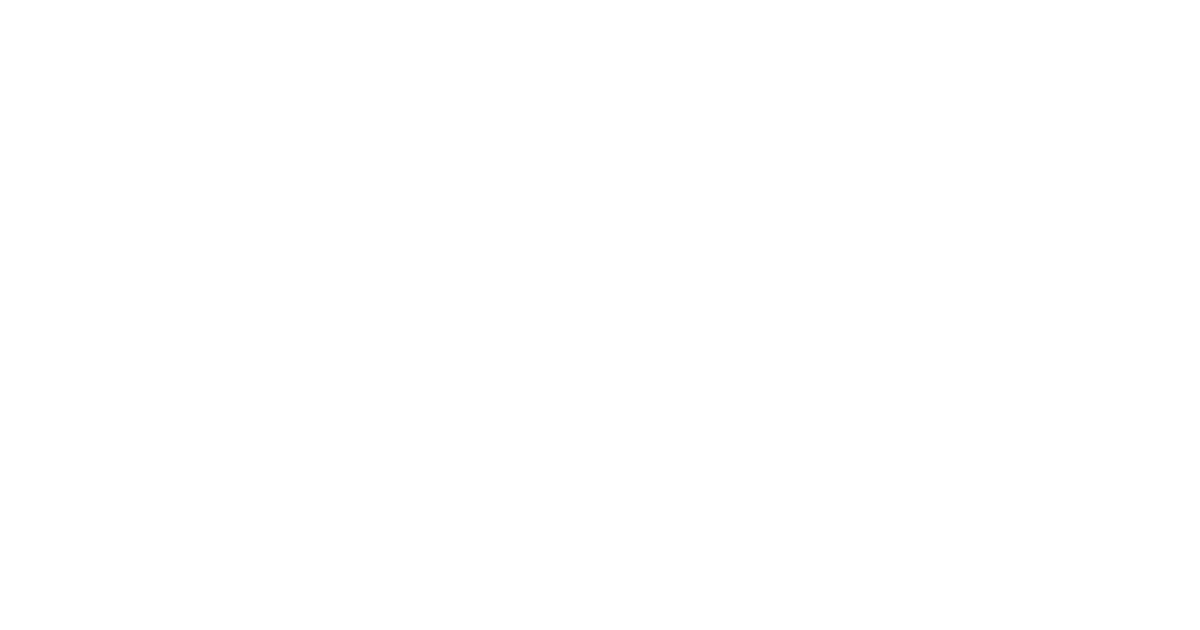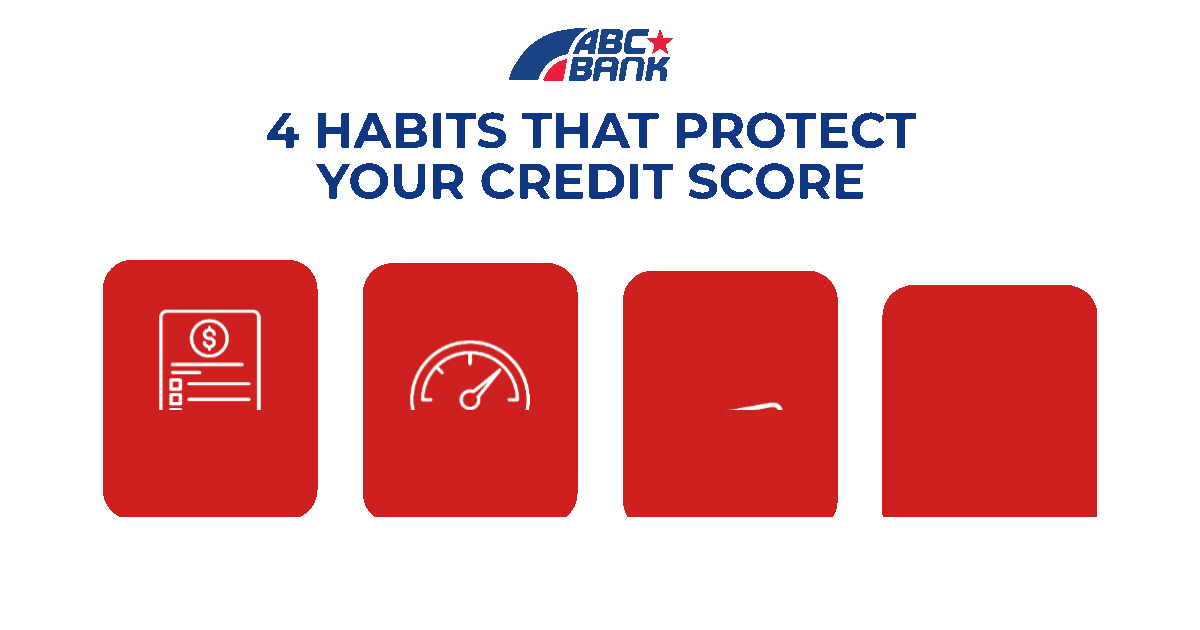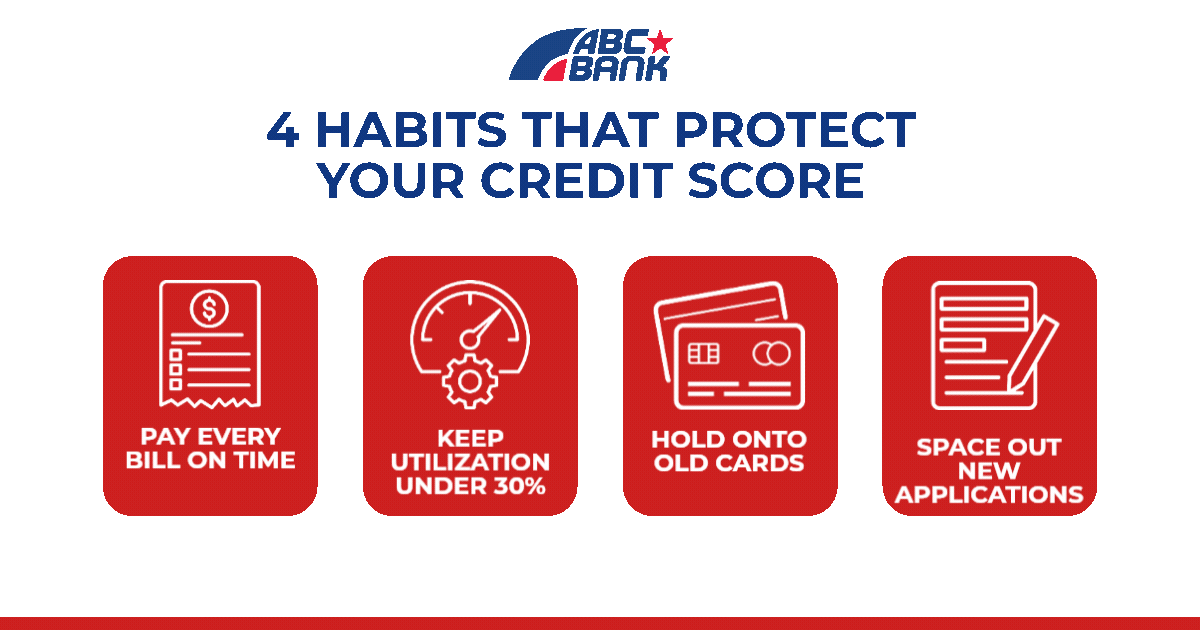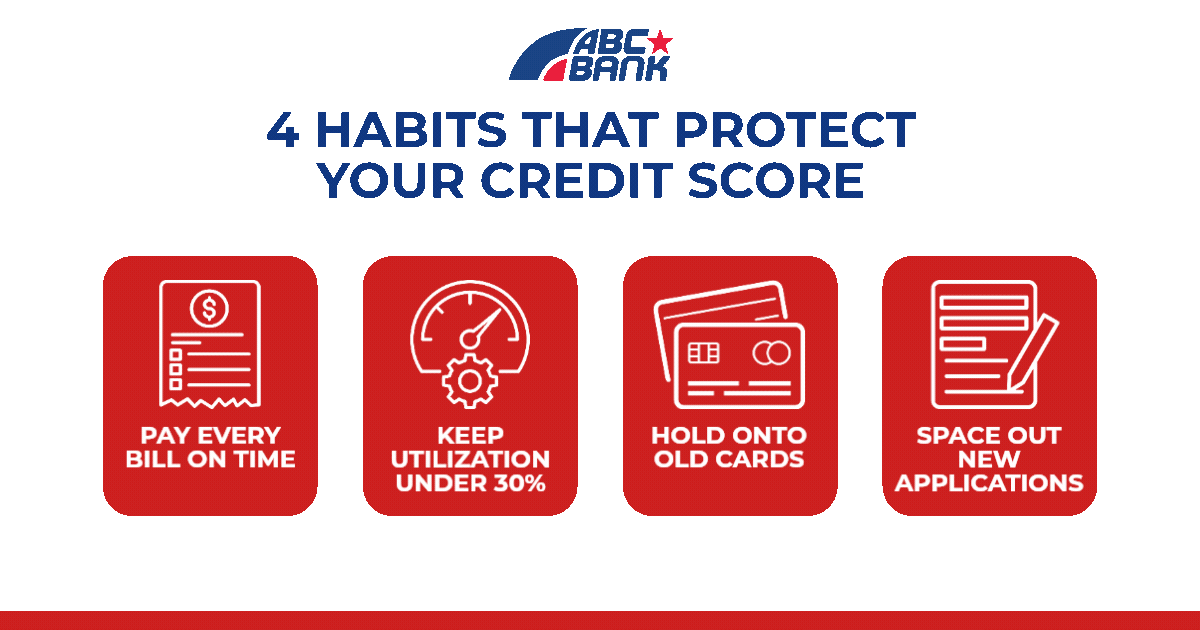
Habits That Build and Protect Your Score
Once you’ve started building credit, a few habits will keep your score moving in the right direction.
Pay Your Bills on Time
Payment history is the single biggest factor in your score. Paying at least the minimum on time matters more than paying extra but late.
Don’t Overuse Your Credit
Keep your balances low relative to your limits. The best scores usually come with utilization under 10%, and staying under 30% is a safe general rule. The closer your balance creeps toward 50% of your limit, the more your score is likely to suffer.
Hold onto Your Credit Cards
It’s tempting to close a credit card you don’t use, but keeping it open usually helps more than it hurts. An old credit card still counts toward your available credit and your length of credit history, both of which support your score. Just use it occasionally, since issuers can close accounts that sit inactive too long.
Limit Your Credit Applications
Applying for several loans or credit cards in a short window signals risk to lenders and can ding your score. Space out applications by six months or more when you can. Each one causes a small, temporary dip that recovers quickly as long as you keep paying on time.
How Long Does It Take to Build Credit?
Most people earn a first credit score within about six months of opening a reportable account. Meaningful improvement from there typically takes another one to two years, depending on your habits. A missed payment here and there will not set you back nearly as much as a consistent pattern of late payments or maxed-out credit cards.
Open an ABC Checking Account Today
If you don’t have a bank account yet, an ABC checking account is a practical first step, giving you a foundation to build from as you take on your first credit card or loan. You can apply online in a few minutes. If you have questions, reach out to us directly or stop by one of our locations in Texas and Colorado. Member FDIC.